Key Points
- It’s a heavy week on the calendar, headlined by Tuesday’s RBA decision, where markets are pricing roughly a 90% chance of a 25 basis point hike to 4.60%, which would be the highest Australian cash rate since 2011, and Friday’s US Non-Farm Payrolls, the single biggest release of the month.
- AUD/USD sits at 0.7027, consolidating just above a demand zone after pulling back from a high near 0.7240 earlier this month. With a hike close to fully priced, it is the RBA’s tone on further tightening into November and December, not the move itself, that carries the real potential to shift the pair.
- Gold is trading at 4,195, having broken below the closely watched 4,240 support (also the 61.8% Fibonacci retracement of its last major leg) to its lowest level in around eight weeks, as the 10 year Treasury yield presses toward 5.2%, its highest since 2007.
Last Week in Review
Last week was dominated by the bond market. The 10 year Treasury yield pushed above 5.2%, its highest level since 2007, and the 30 year approached 5.5%, a level not seen since 2004, as a deepening global bond rout kept fixed income desks on edge. The Swiss National Bank held its policy rate at 0%, as expected, but raised its inflation forecasts across every horizon, citing higher oil prices and a weaker franc. Goldman Sachs sharply reversed its long-standing bearish yen call, cutting its USD/JPY forecasts to 150 in twelve months from 165 previously, while Japanese officials confirmed President Trump had separately raised concerns about yen weakness directly with Prime Minister Takaichi.
Oil had a volatile week, spiking on Houthi strikes on Saudi Arabia before giving back much of that move as Iran floated a seven-day deal on the Strait of Hormuz. Precious metals came under real pressure into the weekend, with gold breaking a key technical support as the surge in Treasury yields deepened the opportunity-cost argument against holding a non-yielding asset, a theme that carries straight into this week.
AUD/USD: Consolidating Ahead of a Live RBA Decision
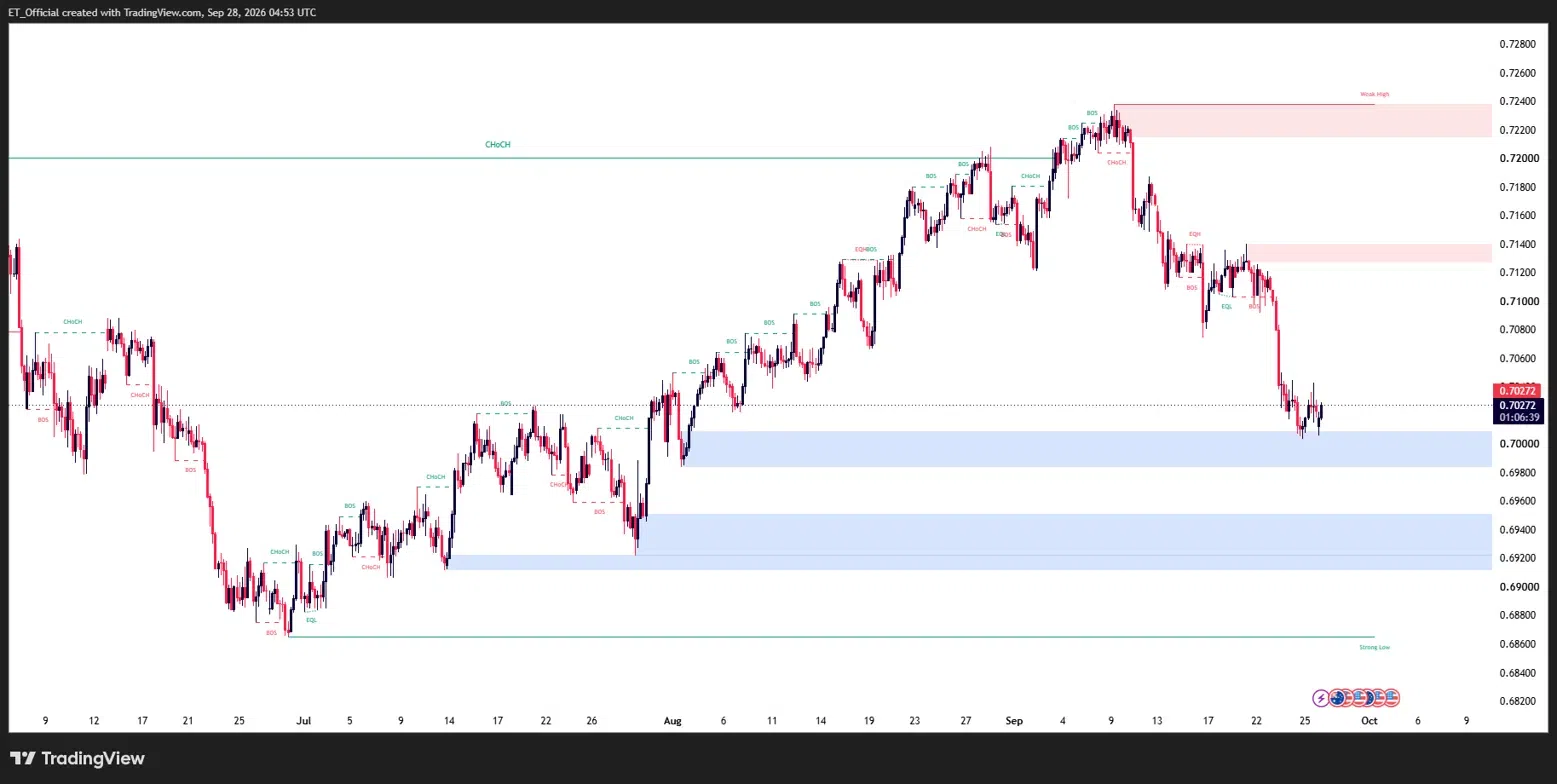
Chart: AUD/USD, Daily timeframe (TradingView, SMC)
The daily chart shows a strong uptrend from a low near 0.6860 in late June, working higher through a series of breaks of structure and changes of character to a high near 0.7240 in early September. A bearish change of character off that high has since carried price back down through the 0.7140 zone to its current level of 0.7027, where it is consolidating just above the 0.6920 to 0.7000 demand zone.
Overhead, the 0.7140 zone is the first resistance to reclaim, with the 0.7240 high the major ceiling further out. Below current price, the 0.6920 to 0.7000 zone is the immediate support being defended, with the 0.6860 low the deeper floor if that fails to hold.
Tuesday’s RBA decision is the defining event for the pair this week. A 25 basis point hike to 4.60% is priced at roughly 90%, with all 29 economists in a recent survey, including Australia’s four major banks, expecting the move, which would mark the fourth hike this year and take the cash rate to its highest level since November 2011. With the hike itself close to fully priced, it is Governor Bullock’s press conference and any guidance on further tightening into November and December, where markets are already pricing at least two more moves, that carries the real potential to shift AUD/USD from here.
Gold: A Key Support Breaks as Yields Bite
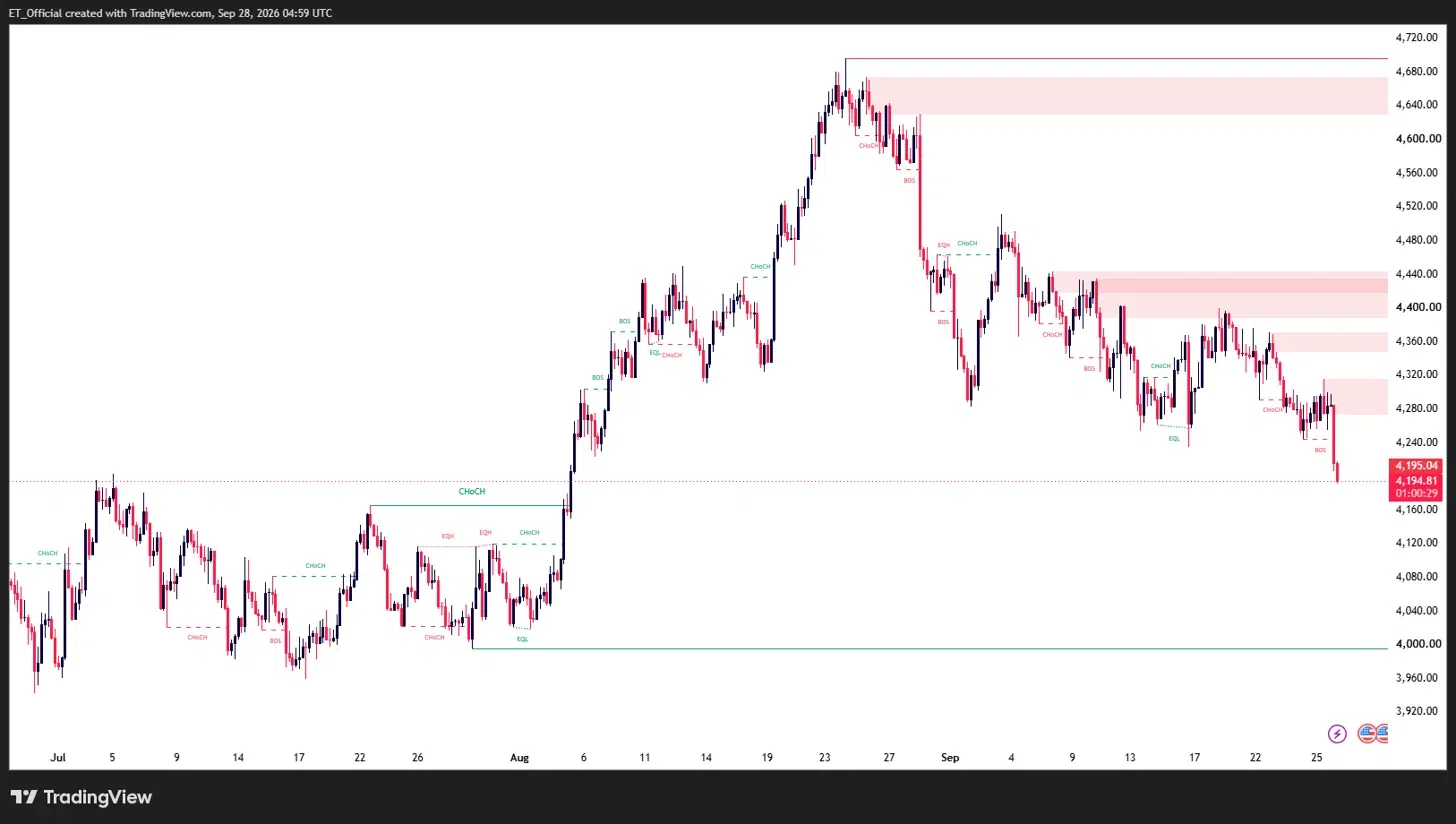
Chart: Gold Spot/USD, Daily timeframe (TradingView, SMC)
The daily chart shows gold’s sharp reversal from a high above 4,700 in late August, breaking down through a sequence of changes of character and consolidating through the 4,240 to 4,400 region for close to two weeks. That support has now broken decisively, with price falling to 4,195, its lowest level in around eight weeks.
Overhead, the broken 4,240 zone is now the first resistance, with the 4,300 to 4,330 area the next zone to reclaim above that. Below current price, there is little clear structure until the psychological 4,000 level, which is the next widely watched target if the current pressure continues.
The driver remains the same one that has been building for weeks: Treasury yields. The 10 year is trading near 5.2%, its highest since 2007, and gold, which pays no yield, becomes an increasingly costly asset to hold as the opportunity cost of forgoing that return grows. With oil prices and geopolitical tensions also reinforcing expectations that policy stays tighter for longer, the path of least resistance stays lower unless yields themselves turn. Friday’s Non-Farm Payrolls report is the week’s biggest wildcard for that yield path, with a weak print potentially doing more to support gold than any single headline this week, and a strong one likely extending the current pressure.
Key Events This Week
Monday 28 September A Quiet Start
No major scheduled releases to open the week, giving markets a chance to digest last week’s yield surge and gold’s technical break before Tuesday’s RBA decision.
Tuesday 29 September RBA Decision and US Consumer Confidence
The Reserve Bank of Australia’s rate decision and Governor Bullock’s press conference are the standout event, with a 25 basis point hike to 4.60% priced at roughly 90%. The US Conference Board Consumer Confidence Index rounds out the session.
Wednesday 30 September Growth Data From Both Sides of the Pacific
A busy session: China’s official and Caixin manufacturing and services PMIs, Japan’s Q3 Tankan survey, German retail sales and preliminary HICP, and UK Q2 GDP final all land through the morning. The US session brings the ADP private payrolls report, the final read on Q2 GDP, and the Fed’s preferred inflation gauge, Core PCE.
Thursday 1 October US ISM Manufacturing PMI
The ISM Manufacturing PMI is the headline US release, offering the first hard read on how manufacturing activity is holding up as yields sit at multi-decade highs. Swiss CPI and Japan’s Tokyo CPI also print through the session.
Friday 2 October US Non-Farm Payrolls
The week’s main event. Non-farm payrolls, average hourly earnings, and the unemployment rate all land at 12:30 UTC, alongside the Eurozone’s flash HICP reading. With the Fed’s rate path already under scrutiny from the bond market, this print carries outsized weight for where Treasury yields, and therefore gold, head into October.
Risk Warning: Trading financial instruments, particularly those involving leverage, involves a substantial degree of risk and is not appropriate for all investors. The value of your investments can rise or fall sharply, and it is possible to lose the entirety of your invested capital. Do not trade with funds you cannot afford to lose. Nothing in this site should be read or construed as constituting advice on the part of Taurex or any of its affiliates, directors, officers or employees.