Key Points
- Gold jumped 2.7% on Wednesday to 4,035 after Democrats won control of Congress and the dollar fell to a one month low, bouncing from a low near 3,867 on 30 October. It still sits below the 4,146 to 4,197 supply zone, and November’s payrolls, CPI and the road to the December Fed will decide whether this is a bounce or a base.
- The Nasdaq 100 is trading about 10% below its 6 October high near 31,350 after the AI trade cracked, with Alphabet, Intel and Amazon all punished for spending, and it fell to 27,493 on Wednesday before recovering to 28,247. The 27,060 low from late July is the next major level below.
- November’s calendar is dominated by the Fed’s December path, with a hike priced at roughly 75% to 87% depending on the source. Payrolls on the 6th, CPI on the 10th, retail sales on the 17th, FOMC minutes on the 18th and PCE inflation on the 25th all feed into the 9 December decision.
October in Review
October’s central bank story was the Fed holding at 3.75% to 4.00% on the 28th in a 10 to 2 vote, with Cook and Hammack dissenting for a hike. Chair Warsh said he was unwilling and unable to call financial conditions tight, the statement upgraded activity to expanding at a strong pace, and Dallas Fed President Logan later called for at least two more quarter point hikes. Third quarter GDP grew 3.4%, September CPI was 3.7% and PCE inflation was 3.6% year on year, which left a December hike priced at roughly 75% to 87% depending on the source.
Energy and geopolitics stayed behind every inflation print. Brent rose almost 14% in October to about $118 a barrel as the US and Iran failed to agree a deal to end their war, while the 10 year Treasury yield fell about 35 basis points over the month to 4.93% after peaking near 5.36% in the first week of October.
The AI trade was the month’s big equity story. The Nasdaq fell 5.3% in October, its worst month since March 2025, while the S&P 500 lost 0.9% and the Dow rose 1.7%, as Alphabet fell 12.6% on negative free cash flow, its worst day as a public company, Intel dropped almost 29% on weak guidance and Amazon’s roughly $77 billion of quarterly capex pushed its free cash flow deeply negative. Microsoft fell only 1.7% as Azure grew 48%, a sign that markets are rewarding returns on AI spending and punishing spending without them.
Gold was the casualty of hike bets and a firm dollar. It fell about 7% in October and closed the month at 3,876.73 after a late bounce to 4,080 failed at supply, and on Friday the 30th it broke the July lows with a drop to 3,867, its weakest level since July. The first days of November brought a sharp reversal, with Democrats winning Congress and the dollar sliding to a one month low.
Gold: Bounce From the Lows Meets Supply
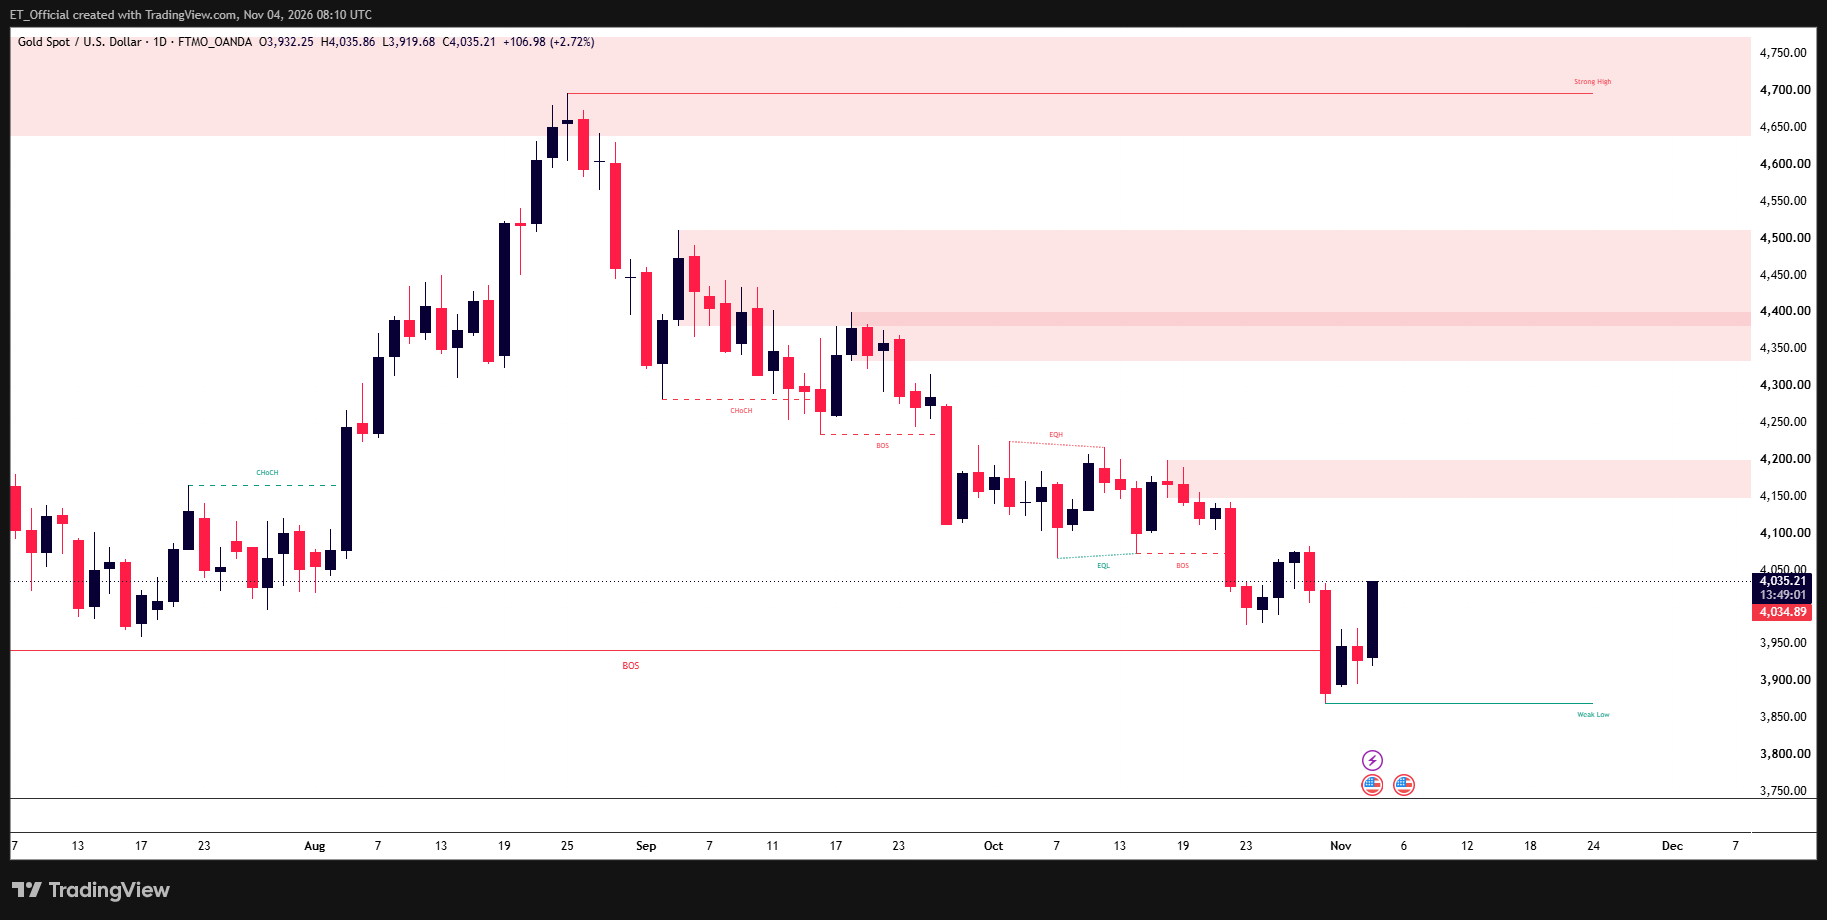
Chart: Gold (XAU/USD), Daily timeframe (TradingView, SMC)
Gold (XAU/USD) daily chart, July to 4 November 2026: price rallied from the 3,940 to 3,960 July lows to a high near 4,695 on 24 August, fell through a series of lower highs to a low near 3,867 on 30 October, and has bounced to 4,035 beneath the 4,146 to 4,197 supply zone.
Zoomed out on the daily chart, the structure is clear. Gold built a base in July around the 3,940 to 3,960 lows, rallied about 19% to a high near 4,695 on 24 August, and has made lower highs and lower lows ever since, rejected from the 4,330 to 4,510 supply zone in September and again from 4,146 to 4,197 in October. The decline broke the July lows on 30 October, leaving a low near 3,867 and a bearish break of structure in place.
The first days of November brought a sharp bounce. Gold jumped about 2.7% on Wednesday to 4,035 after Democrats won control of Congress, the dollar fell to a one month low and yields eased, with analysts linking the move to gridlock slowing US spending and demand for protection against a more unpredictable administration. The next tests are the 4,080 high from 28 October and then the 4,146 to 4,197 supply zone.
That zone is the level for November. A daily close above it would suggest the decline since August is exhausted and open the 4,330 to 4,510 zone, while a rejection would keep the sequence of lower highs and lower lows intact and put the 3,867 low back in play, with 3,850 and 3,800 the round numbers below. The deciding factors are the same ones driving every asset this month: payrolls on the 6th, CPI on the 10th and whether markets keep pricing a December Fed hike.
Nasdaq 100: The AI Trade Cracks
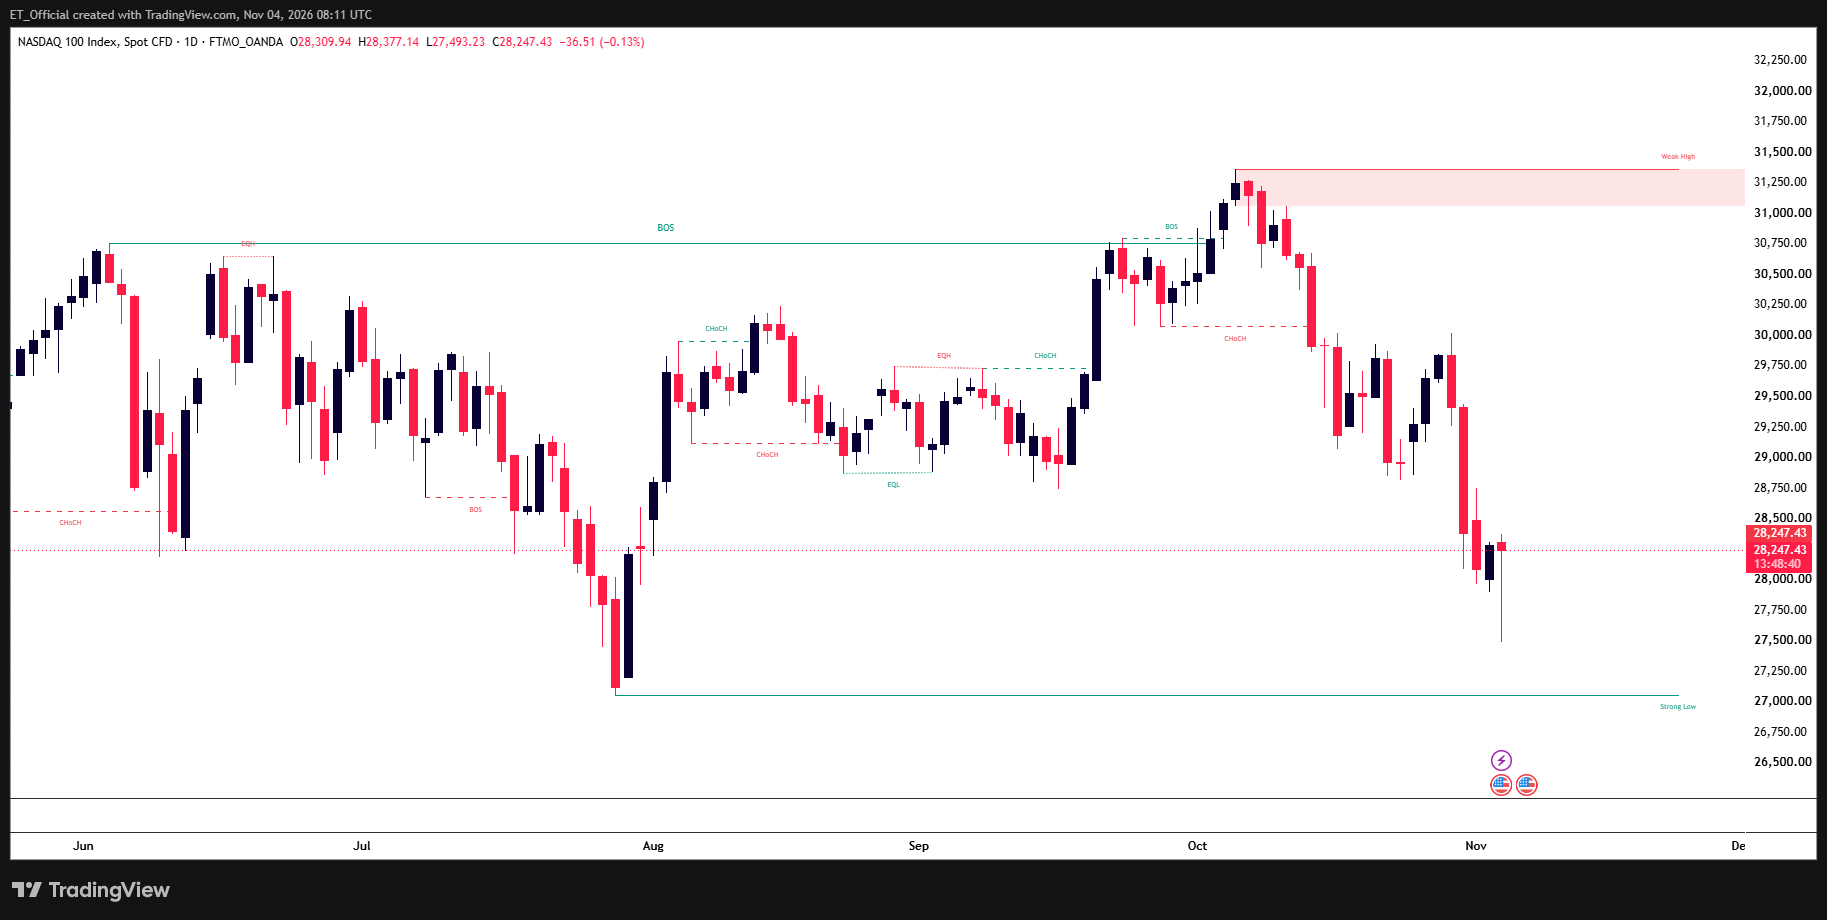
Chart: Nasdaq 100 Index (US100), Daily timeframe (TradingView, SMC)
Nasdaq 100 (US100) daily chart, June to 4 November 2026: the index broke out of its August to September range to a high near 31,350 on 6 October, then fell about 12% to a low near 27,493 on 4 November, and is trading at 28,247 with the 27,060 low below.
The AI trade that carried the index to a high near 31,350 on 6 October has cracked. After a range between roughly 28,700 and 30,300 through August and September, the Nasdaq 100 broke out in late September, was rejected from the 31,050 to 31,350 supply zone, and then gave back the whole breakout, falling through the range in October to trade at 28,247, about 10% below the high.
Early on Wednesday the index dropped to 27,493, a fall of about 12% from the high, as Democrats took Congress and traders worried that a sweep could disrupt the AI data centre buildout, before recovering to 28,247 and leaving a long lower wick. That wick matters, because buyers stepped in well above the 27,060 low from late July, which is the next major level below.
The debate is whether this is a correction or the start of something deeper. Hyperscaler capex of just over $200 billion exceeded operating cash flow by about $26 billion last quarter, against about $60 billion of cash left over a year earlier, so the market is pricing returns on spending more closely. Above, 28,700 to 29,000 is the first resistance and the 31,050 to 31,350 zone caps any full recovery, while a daily close below 27,493 would put the 27,060 low in play.
What to Watch in November
A quick guide to every major event this month and what it could mean for markets.
Bank of England Rate Decision (Thursday 5 November)
The Bank of England is expected to raise Bank Rate by 25bp to 4.00% from 3.75% at 12:00 UTC, after holding 6 to 3 in July and September with three members voting for a hike. The vote split and guidance matter more than the move itself, with analysts expecting the Bank to push back on market pricing of more than four hikes over the next year, which will decide whether GBP/USD, near 1.34, extends its rebound.
US Non Farm Payrolls (Friday 6 November)
October’s jobs report is forecast at roughly 55,000 to 65,000 jobs after 29,000 in September, with unemployment near 4.2%. With a December hike priced at about 75% to 87%, a strong print with firm wages would reinforce it and pressure gold, while a weak print could cut hike odds and extend the dollar’s slide.
US CPI (Tuesday 10 November)
October CPI follows September’s 3.7% year on year print, and with Brent up almost 14% in October, energy is the number to watch in the headline. A hot core reading would keep the December hike case alive, while a softer one would give the Fed room to wait and support gold and the Nasdaq 100.
US Retail Sales (Tuesday 17 November)
October retail sales test whether the consumer is holding up against inflation near 3.7% and mortgage rates above 7%. A weak print would add to the growth concerns that have weighed on Treasury yields and equities, while a strong one would support the hawkish case at the Fed.
FOMC Minutes (Wednesday 18 November)
The minutes from the 27 to 28 October meeting, released at 19:00 UTC, will show how divided the committee is after the 10 to 2 vote and how seriously members are considering a December hike. Any sign that more officials lean towards tightening would lift the dollar and pressure gold.
US GDP and PCE Inflation (Wednesday 25 November)
The second estimate of third quarter GDP, previously 3.4%, lands alongside October PCE inflation, the Fed’s preferred gauge, after September’s 3.6% reading. It is the last major inflation print before the Fed meets, so it will shape how firmly a December hike is priced, and with US markets closed on Thursday 26 November for Thanksgiving, liquidity thins into month end.
The Iran and Hormuz Question
The US and Iran remain far from a deal to end their war, and Trump has not ruled out resuming combat, keeping the Strait of Hormuz and Gulf supply at the centre of oil’s risk premium. Brent rose almost 14% in October to about $118 and has since eased, so a deal or a breakdown in talks would move oil sharply and with it inflation expectations, yields and gold.
AI Spending and Big Tech Earnings
October’s earnings showed markets separating AI spending that earns a return from spending that does not, and the chip results due later in the month are the next test, with Nvidia expected to report in the second half of November (date to be confirmed). Further disappointments would pressure the Nasdaq 100 toward the 27,060 low, while a strong report could help it recover the 28,700 to 29,000 area.
The December Fed and the Funding Deadline
The Fed meets on 8 to 9 December, and everything in November builds towards it, with Polymarket pricing about a 75% chance of a 25bp hike and about 24% for no change. Government funding also runs out on 11 December, which adds fiscal headline risk now that Congress has changed hands.
Key Dates
All times shown in UTC.
| Date | Time (UTC) | Event | Detail |
| Thu 5 Nov | 12:00 | BoE Rate Decision (GBP) | Hike to 4.00% expected |
| Fri 6 Nov | 13:30 | Non Farm Payrolls (USD) | Forecast 55K to 65K, previous 29K |
| Tue 10 Nov | 13:30 | CPI (October data) (USD) | Key read for the December hike |
| Tue 17 Nov | 13:30 | Retail Sales (USD) | Consumer demand test |
| Wed 18 Nov | 19:00 | FOMC Minutes (USD) | From the 27 to 28 October meeting |
| Wed 25 Nov | 13:30 | GDP and PCE Inflation (USD) | Q3 GDP, October PCE |
| Thu 26 Nov | All day | US Thanksgiving (USD) | US markets closed, thin liquidity |
Risk Warning: Trading financial instruments, particularly those involving leverage, involves a substantial degree of risk and is not appropriate for all investors. The value of your investments can rise or fall sharply, and it is possible to lose the entirety of your invested capital. Do not trade with funds you cannot afford to lose. Nothing in this site should be read or construed as constituting advice on the part of Taurex or any of its affiliates, directors, officers or employees.