Key Points
- Netflix, Meta and Tesla headline a week of earnings that will show whether the AI spending worries behind last week’s sell-off are easing, with Netflix reporting Tuesday and Meta and Tesla on Wednesday, alongside UK CPI.
- The Nasdaq 100 is trading at 29,574.9, bouncing from a Friday low near 29,050 after falling about 7% from its early-October high near 31,350, with the 29,810 to 30,010 supply zone now overhead.
- WTI crude is at 97.52, up from a low near 87.20 on 6 October, with a Russian oil sanctions waiver and tanker incidents near Hormuz pulling in opposite directions a week before the Fed meets on 27 and 28 October.
Last Week in Review
US inflation data ran hot. September CPI rose 3.7% year on year with core at 2.6%, producer prices jumped 1.3% on the month, the biggest rise since March 2022, and retail sales rose 0.8%. The 10-year Treasury yield nonetheless fell from above 5.2% to around 5.1%, its largest weekly drop in over eight months, and the Dollar Index slipped to about 101.8.
Fed Chair Kevin Warsh gave no explicit guidance on the 27 to 28 October meeting when he spoke in Bangkok on Friday, and the Fed is now in its blackout period. Markets price about a 27% chance of a hike this month and still lean toward one by December.
Equities split. The Dow rose 0.7% while the S&P 500 fell 1.9% and the Nasdaq Composite fell 4.5%, with the Philadelphia Semiconductor Index down 11.4%, its longest losing streak since 2008, as investors questioned AI’s funding needs. The sell-off spread to Asia, where the Nikkei lost 5.4% and South Korea’s market more than 14%.
Nasdaq 100: Bouncing From a 7% Drawdown Into Earnings
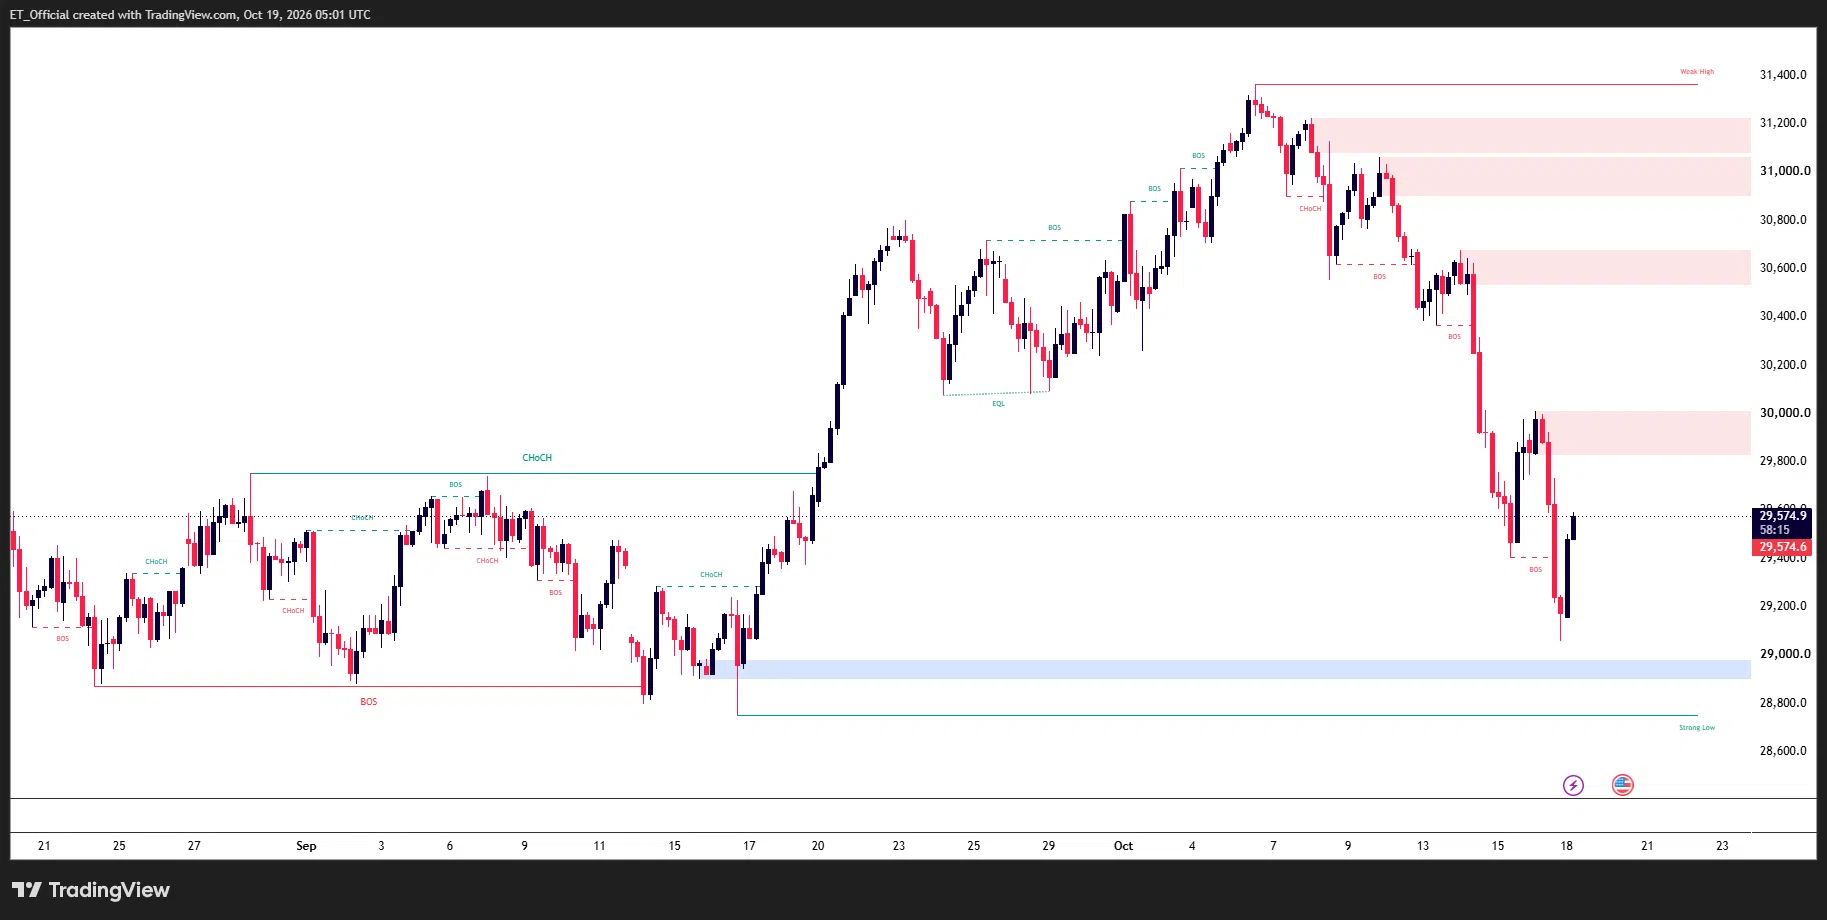
Chart: Nasdaq 100 (US100), 4H timeframe (TradingView, SMC)
Nasdaq 100 (US100) 4H chart, 21 August to 19 October 2026: price rallied from a low near 28,740 on 17 September to a high near 31,350 in early October, fell about 7% to a low near 29,050 on 16 October, and is now trading at 29,574.9 below the 29,810 to 30,010 supply zone.
The 4H chart shows the index rallying from a low near 28,740 on 17 September to a high near 31,350 in early October, then reversing sharply. Price broke structure lower after that high, was rejected from three supply zones between 30,530 and 31,225, and fell to a low near 29,050 on Friday.
The bounce has carried price to 29,574.9, but the relief rally late last week stalled at 30,010, inside the 29,810 to 30,010 supply zone, before turning lower. That zone is the first level bulls need to reclaim, and Netflix on Tuesday and Meta on Wednesday are the likely tests of whether the AI spending worries are easing.
Below current price, the 28,890 to 28,970 demand zone and the 17 September low near 28,740 are the levels to hold, and a break below Friday’s 29,050 low would bring them into play. Overhead, 30,530 to 30,675 is the next supply zone, then 30,900 to 31,060 and 31,085 to 31,225, with the early-October high near 31,350 above them.
WTI Crude: Higher Lows Meet Sanctions Relief
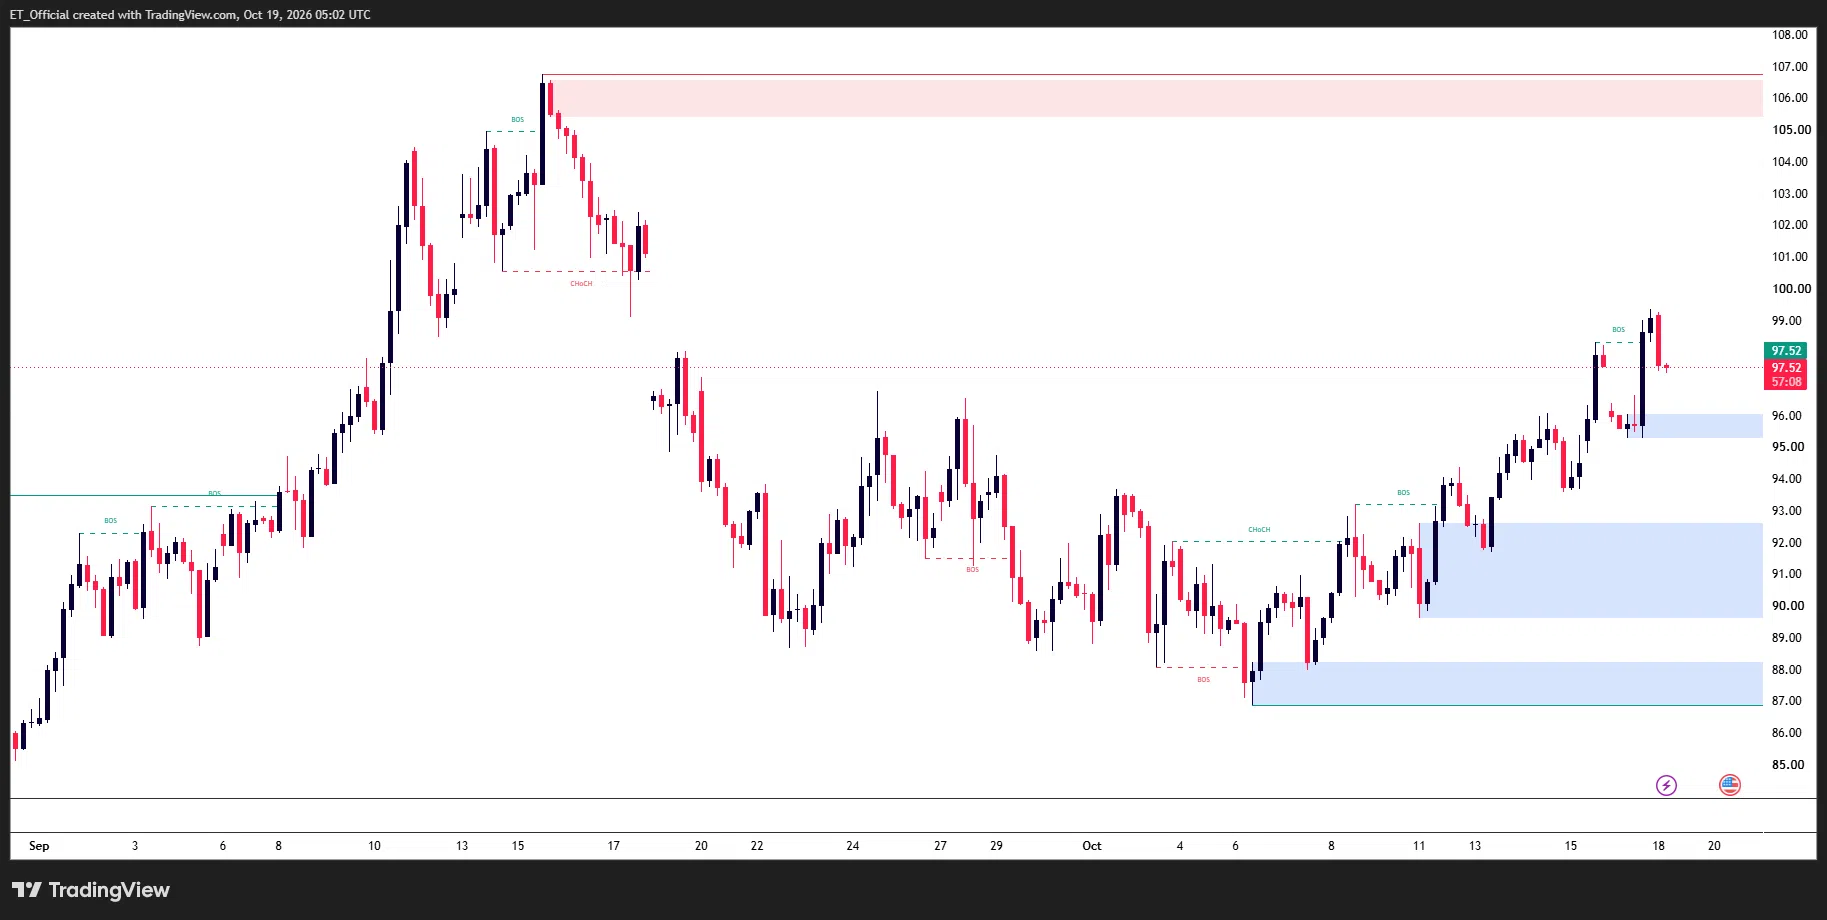
Chart: WTI Crude Oil, 4H timeframe (TradingView, SMC)
WTI crude oil 4H chart, 1 September to 19 October 2026: price spiked to a high near 106.50 on 16 September, fell to around 89, made a low near 87.20 on 6 October, then rallied through higher lows to 99.30 on 16 October and is now trading at 97.52.
The 4H chart shows a spike to a high near 106.50 on 16 September, rejected from the supply zone at 105.25 to 106.40, followed by a drop of about 16% to near 89 within a week. Price then ranged between roughly 87 and 97 for two weeks, making a low near 87.20 on 6 October before reversing higher.
Since then price has built a staircase of higher lows, with the demand zones at 89.70 to 92.60 and 95.30 to 96.00 holding, and reached 99.30 on Friday, about 14% above the October low. The pullback to 97.52 ended a seven-day winning streak and came as the US waived some Russia oil sanctions, with up to 60 days to assess the impact, even as three tankers were damaged near the Strait of Hormuz over the weekend and Iran says the route remains closed to unauthorised traffic.
Oil matters for this week’s inflation data and for the Fed, with producer energy prices up 10.8% in September’s PPI, including a 20.3% jump in gasoline, and UK CPI on Wednesday expected to rise on fuel and airfares. A hold above 95.30 keeps the higher-low structure intact, while a break below 92.60 would suggest the sanctions waiver is winning. Above, 99.30 and then the 105.25 to 106.40 supply zone are the levels to watch.
Key Events This Week
Monday 19 October China GDP and Canada CPI
China’s third quarter GDP came in at 4.5% against a 4.4% forecast, with retail sales up 1.1% and industrial output up 5.5%, and the yuan firmed to its strongest since July 2022. Canada’s September CPI is also due, after a weak jobs report lowered expectations of a Bank of Canada rate hike.
Tuesday 20 October UK Jobs and Netflix
UK jobs data are due at 06:00 GMT, with the unemployment rate last at 4.9%, alongside German ZEW sentiment, China’s loan prime rate and US housing starts. Netflix reports after the US close, with consensus at about $12.88 billion revenue and $0.83 earnings per share, an options-implied move of about 8.4%, and attention on advertising revenue and margins.
Wednesday 21 October UK CPI, Meta and Tesla
UK September CPI is due at 06:00 GMT, expected to rise to about 3.4% from 3.1%, ahead of the Bank of England’s 5 November meeting, where a hike is largely priced. Meta and Tesla report after the US close. Meta is expected to post about $63.3 billion revenue with 2026 capex guided at $130 to $145 billion, and Tesla about $0.43 earnings per share on $27.9 billion revenue.
Thursday 22 October Central Bank Holds and Jobless Claims
The Bank of Korea is expected to hold at 3.00% and Turkey’s central bank at 37%, with US jobless claims, SNB minutes and Australian flash PMIs also due. It is a lighter data day, so earnings reactions and oil headlines are likely to drive price.
Friday 23 October Flash PMIs, Japan CPI and Moody’s on France
Global flash PMIs for October are due, with eurozone manufacturing and services both expected around 52.5 to 53.3, alongside Japan’s September CPI, forecast at 2.8 to 3.0% against 1.9% before, the last major print before the Bank of Japan meeting. Moody’s reviews France, rated Aa3 with a negative outlook, and UK retail sales and US Michigan sentiment also land.
Risk Warning: Trading financial instruments, particularly those involving leverage, involves a substantial degree of risk and is not appropriate for all investors. The value of your investments can rise or fall sharply, and it is possible to lose the entirety of your invested capital. Do not trade with funds you cannot afford to lose. Nothing in this site should be read or construed as constituting advice on the part of Taurex or any of its affiliates, directors, officers or employees.